
Market Movers
Last week, 519 originators switched companies and 1,244 individuals obtained their NMLS license. Notable originator movements last week include:
- Allyson Cain ($177.6M, 744 units) joined Canopy Mortgage, LLC
- Ashley Mckenzie ($174.5M, 577 units) joined CrossCountry Mortgage, LLC
- Thomas Blalock ($126M, 233 units) joined Republic State Mortgage Co.
- Rolando Garcia ($106.5M, 332 units) joined FIRST HERITAGE MORTGAGE, LLC
- Apexa Patel ($105.1M, 320 units) joined i Lending Inc.
- Tyler Hodgson ($91.4M, 210 units) joined NEXA Mortgage, LLC
- Melvin Johanis ($84.3M, 219 units) joined West Capital Lending, Inc.
- Nicolas Toscano ($82.2M, 189 units) joined Match Mortgage Co
- Christy Bencivenga-Burns ($78.9M, 190 units) joined Atlantic Bay Mortgage Group, L.L.C.
- Angel Perez ($78M, 227 units) joined West Capital Lending, Inc.
- Jeremiah Sherer ($73.7M, 14 units) joined American Neighborhood Mortgage Acceptance Company LLC
- Eric Glick ($73.1M, 187 units) joined Southeast Mortgage of Georgia, Inc.
- Stacy Rose ($65.3M, 171 units) joined Ark-La-Tex Financial Services, LLC
- Tyler Howe ($62.4M, 118 units) joined Rate
- Yuko Omorai ($62.3M, 96 units) joined Rate
- Andrew Simmons ($59.8M, 132 units) joined NBI Financial Group LLC
- Angelina Martinez ($58.2M, 232 units) joined Fairway Independent Mortgage Corporation
- Brad Andrews ($57.9M, 154 units) joined loanDepot.com, LLC
- John Thompson ($57.3M, 51 units) joined Better Mortgage Corporation
- Benjamin Dodson ($54.5M, 158 units) joined West Capital Lending, Inc.
- Carrie Dixon ($53.7M, 116 units) joined Fairway Independent Mortgage Corporation
- Hunter Gilmore ($49.5M, 120 units) joined Fairway Independent Mortgage Corporation
Figures are based on last 14 months’ production.
Market Movers (Gainers by Producer Volume)
Top Gainers (non-Bank/CU):
- Southeast Mortgage of Georgia, Inc. +17.79%
- Republic State Mortgage Co. +16.27%
- NEXT WAVE MORTGAGE, LLC +12.57%
- Rosegate +9.28%
- Thrive Lending LLC +9.08%
- Promise Home Loans, Inc. +6.85%
- Ladera Lending, Inc. +6.35%
- Renovation Finance LLC +6.02%
- Origna8 Mortgage LLC +5.79%
- ZOOM HOME LENDING LLC +5.16%
- NEXA Mortgage, LLC +4.57%
- Canopy Mortgage, LLC +4.02%
- Standard Mortgage Capital LLC +3.6%
Calculations based on last aggregate production of individual LO’s 14 months’ production. Excludes companies below $100M in 14mo LO production value after gains factored in.
How Much Warning Is There Before an Agent Relationship Changes?
Part 3 of our Agent Loyalty & Risk Series
In Part 1, we found that high-producing agent relationships move more than many loan officers might expect.
In Part 2, we found that higher Agent Risk Scores were strongly associated with a greater likelihood of another LO taking the #1 position.
That raised the next question:
How much warning do you actually get before the relationship changes?
To find out, we reversed the analysis. We identified agent relationships where a different loan officer moved into the #1 position and remained there for at least three consecutive monthly snapshots.
Then we looked backward.
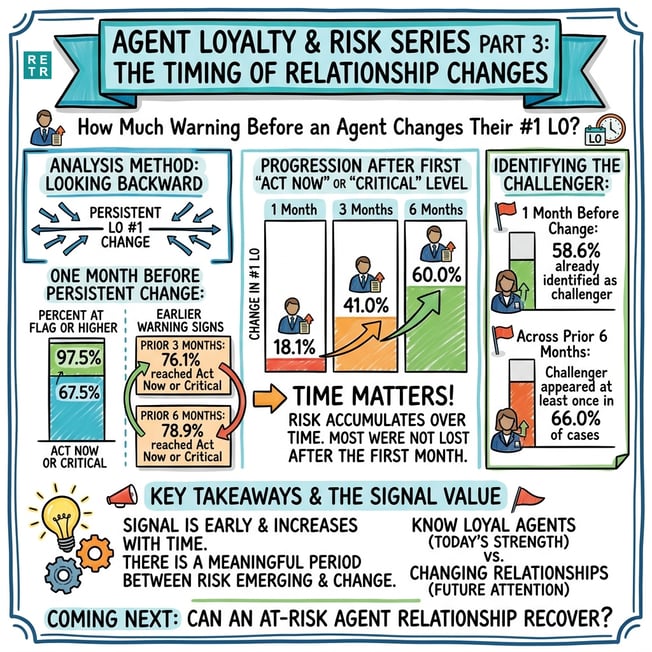
One month before those persistent changes:
97.5% were already at Flag or higher.
67.5% were already at Act Now or Critical.
And the warning often appeared earlier than that.
76.1% had reached Act Now or Critical at least once during the prior three months.
78.9% had reached that level at least once during the prior six months.
We also looked at what happened after an agent first reached Act Now or Critical.
18.1% experienced a change in their #1 LO within one month.
41.0% experienced a change within three months.
60.0% experienced a change within six months.
That progression may be the most important finding.
An elevated Risk Score does not necessarily mean the relationship is already lost. In fact, most had not changed after the first month.
But as time passed, the likelihood of a change increased substantially.
We could often see who was gaining ground as well.
One month before a persistent change, the LO who eventually became #1 was already identified as the challenger in 58.6% of cases.
Across the prior six months, the eventual winner appeared as the challenger at least once in 66.0% of cases.
That suggests there is often a meaningful period between the emergence of Risk and an eventual change in the relationship.
And that may be the real value of the signal.
Knowing who your loyal agents are tells you where your strongest relationships stand today.
Knowing which of those relationships are beginning to change may tell you where your attention should go next.
Which brings us to Part 4:
Can an at-risk agent relationship recover?
Upcoming RETR Training
-
- Mon, Sep 14 @ 2p ET - Intro to RETR: The Modern Loan Officer’s Data Advantage Register
- Wed, Sep 16 @ 1p ET - How to Win Realtor Relationships with RETR Register
Is RETR Better?
When it comes to mortgage market intelligence, you have a handful of options, and RETR is one that truly stands out. Here’s what Michael Puorro, a top producer at Embrace Home Loans has to say about RETR: “RETR really is better! I’ve tried other realtor/mortgage data systems and none of them were as complete for my market area. RETR is organized in a simple and easy way, making it super easy to navigate multiple accounts and pull up data. The insight I get into new and existing referral sources is paramount to my business and I wouldn’t know how to operate without it!”
But you don’t have to take their word for it. RETR offers a free trial to individuals and organizations to judge the quality of the data and insights for themselves.